

Lydian is a synthetic fuels company. We make jet fuel from carbon dioxide, hydrogen, and electricity. For the first time, we’re sharing a long-form version of our thesis on why this is worth doing and how we’ll make it cost-effective.
Introduction - the future of liquid fuels demand
Electrification is on the cusp of radically changing the demand for liquid fuels. EVs now account for a quarter of global new vehicle sales and over 50% in China, the world’s largest car market. [1] China is also increasingly exporting its low-cost EVs to the rest of the world. China has already exported 2.4 million EVs in the first half of 2026, more than all of 2025. [2] China had almost no auto exports just over 5 years ago; now their EV exports alone are a multiple of total U.S. passenger vehicle exports. [3]
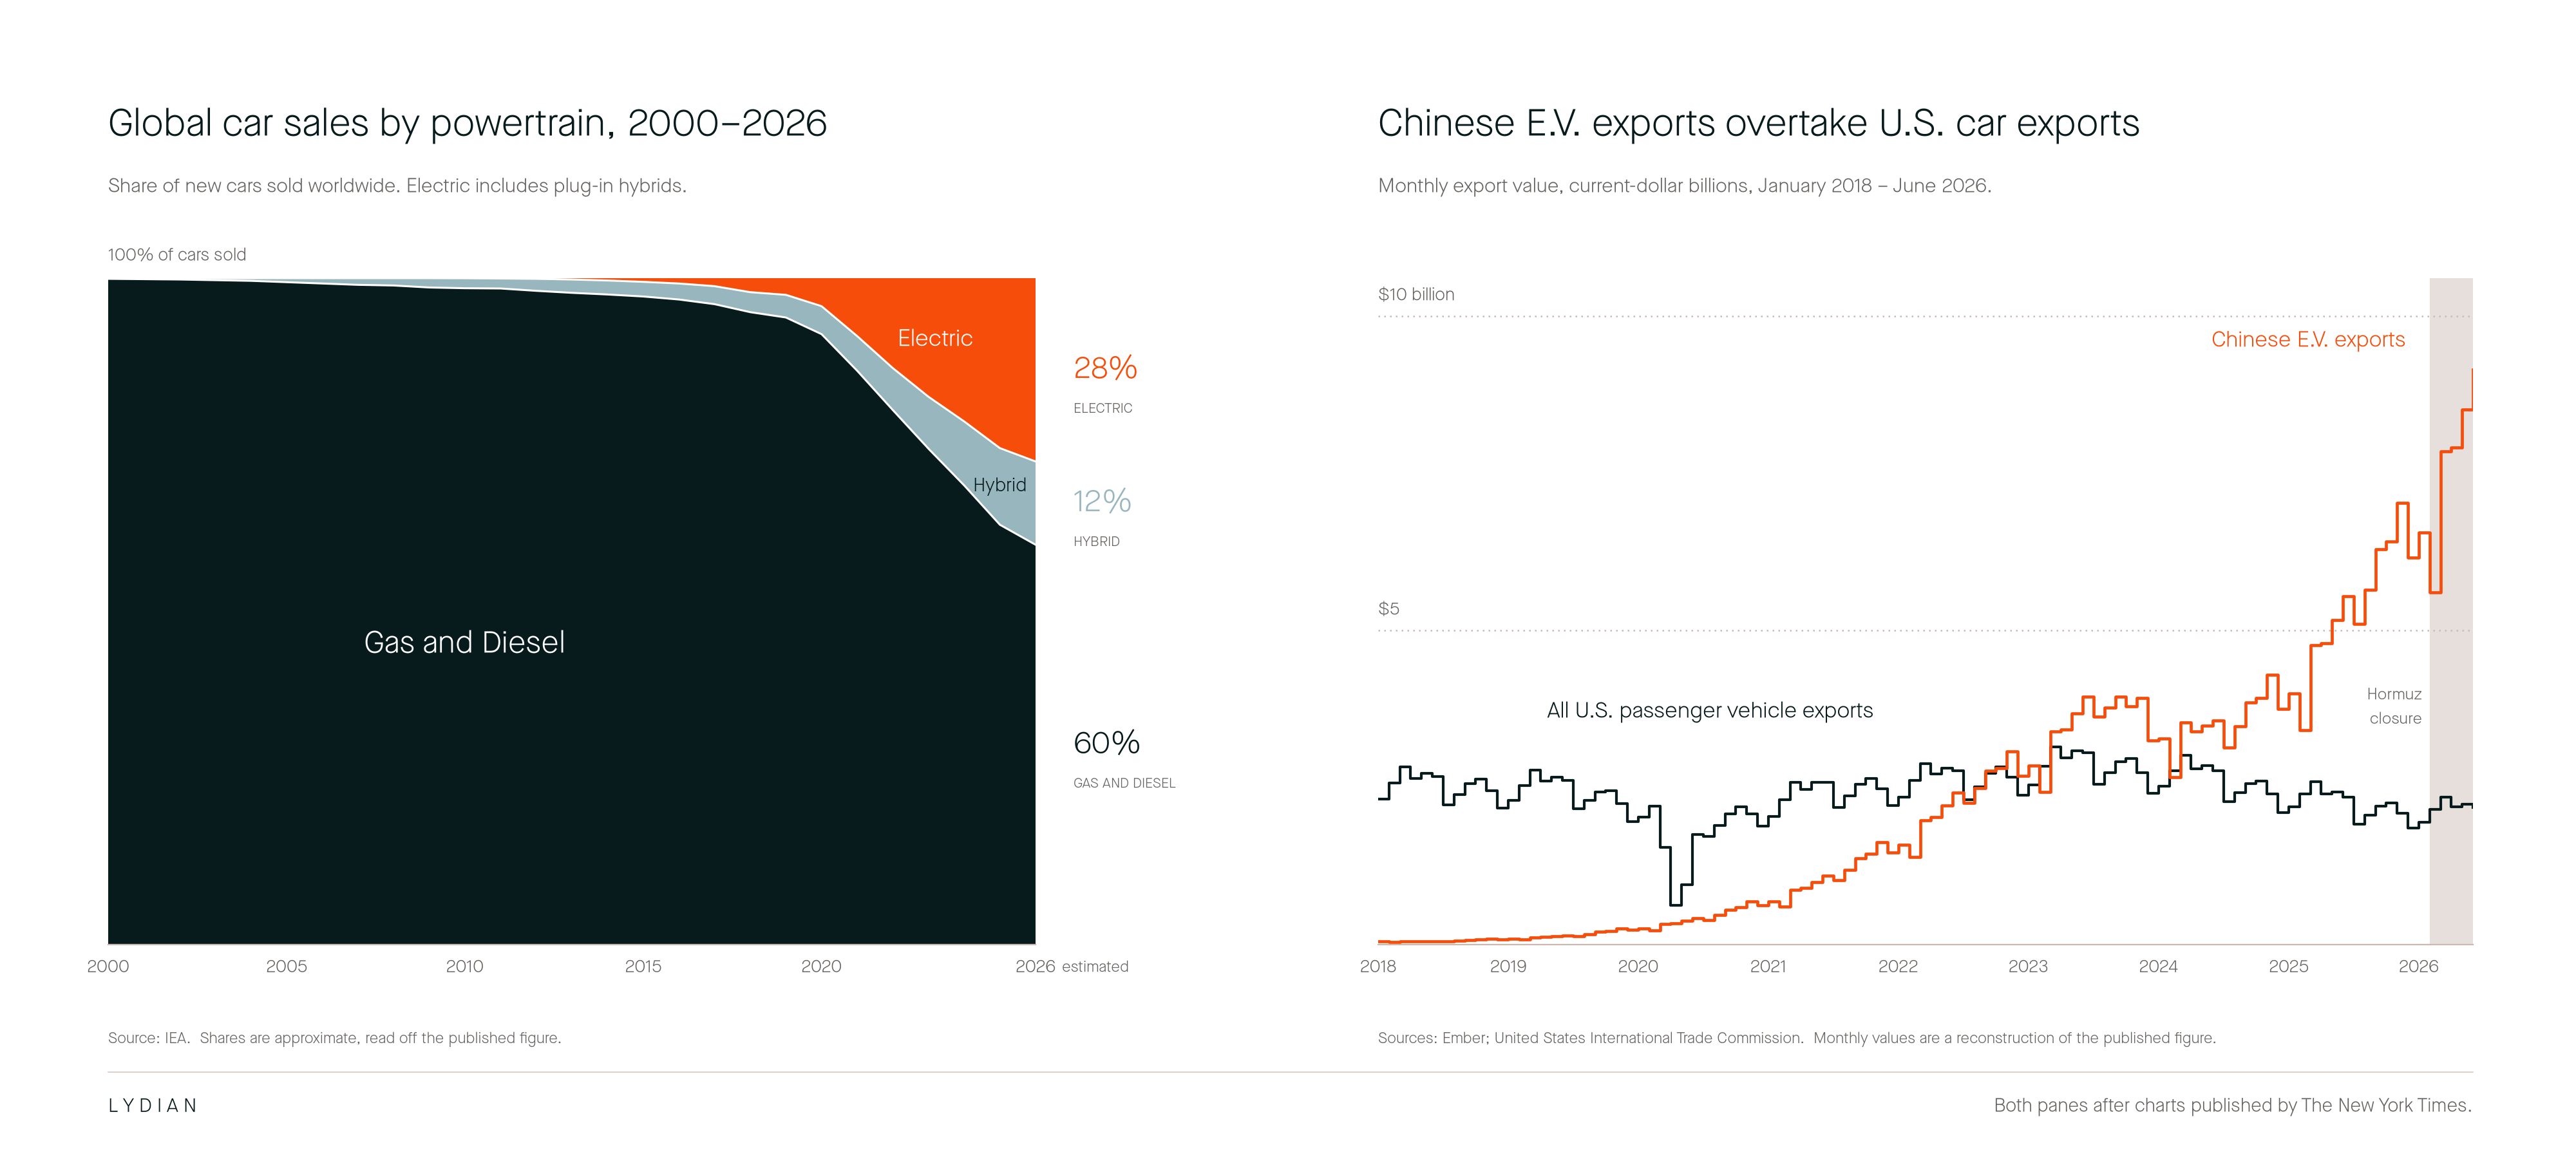
The electrification of medium and heavy duty trucking is starting to pick up speed, too. Megawatt-scale charging infrastructure is proving slow to build in the West and will set the timeline there [4], but again, different story in China: the country recently announced that by 2030, EVs will make up 40% of new heavy truck sales. On some short-haul routes, the target is 80%. [5] And because commercial fleets turn over faster than passenger vehicles, this transition will not take as long once it is in full swing. Similar trends are playing out in the motorcycle, moped, and scooter markets in places like Southeast Asia, where up to 85% of households own a two-wheeler. [6]
You get the idea — the vast majority of ground transportation will be electric in the not-so-distant future. The EIA predicts that US gasoline demand already peaked in 2017-18 [7] and many international bodies are predicting that global demand will peak in the next few years. [8]
This is not good news for refineries. 75-85% of what refineries produce ends up getting burned as fuel, and more than half of that fuel goes to road transport. [9] Refineries in the West are already under stress from aging equipment, higher energy, labor, and emissions costs, and lower efficiency and integration compared to newer Asian refineries. [10] U.S refinery closures since 2019 have permanently removed over 1.2 million b/d of crude processing capacity [11], and refining capacity fell again during 2025. [12] Wood Mac estimates that approximately a quarter of global refining capacity is at risk of closing in the next decade, most of it in the West. [10]
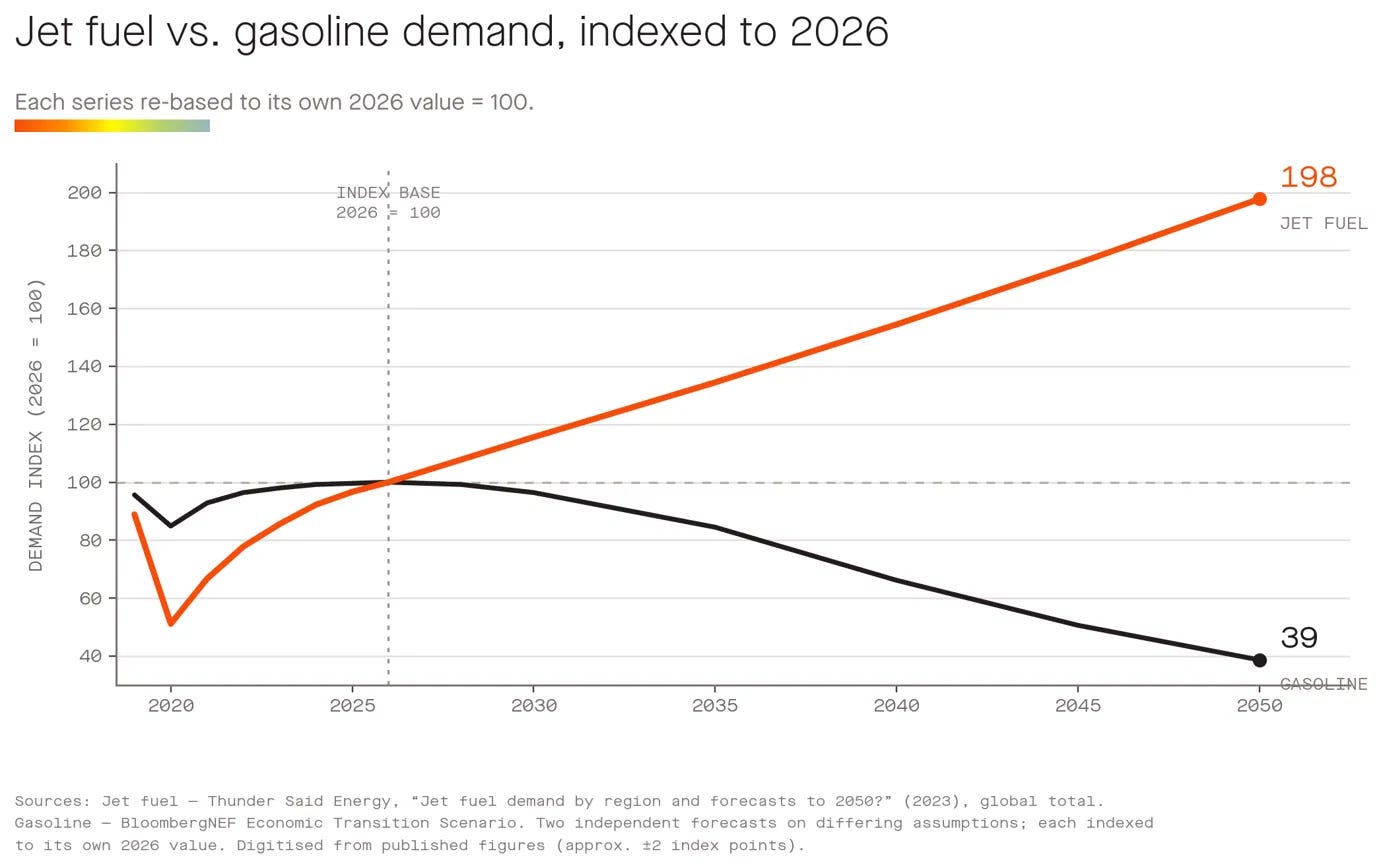
Jet fuel, on the other hand, is not replaceable with electrification and continues to see strong global demand growth. It’s estimated that perhaps 80% or so of the global population has never been on an airplane [13] and only about 10% fly in a given year, meaning there is considerable headroom for demand growth as the developing world gets richer. The result is that jet fuel consumption is expected to double between now and 2050, while demand for gasoline will contract by 60% or more. [14]
In general, refineries have surprisingly little ability to flex their product slate without major capital upgrades. Gasoline-leaning cracking refineries account for about 50% of global capacity and produce ~10% jet fuel with perhaps a couple percentage points of flexibility. Deep conversion refineries can achieve a higher share and slightly more flexibility, stretching jet output to perhaps just shy of 20%. [15] The recent closure of the Strait of Hormuz gives a good sense check on overall refinery product flexibility. Jet crack spreads widened considerably in the early weeks of the conflict compared to other refined products; USGC spreads tripled from $0.42/gal to $1.25/gal, driven in large part by a steep premium for jet in Europe and Asia, which pulled American product across the Atlantic and Pacific. [16] U.S. refiners responded by increasing jet yields as much as they could to maximize profits: average production crossed 2.0 million b/d for the first time on record in the week ending 1 May, up from 1.7 million b/d before the closure. [16] But despite a glaring price signal favoring jet production, the USGC jet fuel share during the Hormuz conflict increased by less than 2 percentage points of output. [17] That’s not nearly enough - jet fuel’s share of the barrel is likely to increase by 10% or more over the next couple of decades.
All of this - stretched margins, lower demand for major products, and significant capital outlays to increase flexibility - points to a higher long-term cost for jet fuel. Holding margins equal against declining refined product demand and shifting mix, and accounting for supply closures, we estimate that jet prices will increase over time by up to $2/gal. When someone asks us about “jet parity” at Lydian, this is how we think about it - before any environment or energy security premium, structural trends favor the long term cost of jet fuel being closer to Hormuz levels ($4-5/gal) than historical levels ($2-3). [18]
This is an opportunity for new technologies that can selectively produce jet fuel and not much else at an attractive cost, especially if those technologies also have other benefits which have market value.
Biofuels
Biofuels today supply about 1,400 TWh of energy, less than 1% of total energy consumption (~600 EJ). And less than 1% of biofuel energy goes to aviation. [19] Clearly, increasing the share of jet fuel from bio-based sources is an opportunity as we transition to electric for ground transport. And this begs the question - why not supply all of our jet fuel that way?
The common argument is that biofuels are supply constrained. This is not strictly true - we could produce more than enough biomass to supply all the energy for aviation. A related argument that’s more true is that cost-effective feedstock for biofuels is supply constrained. Biomass is not created equal - some biomass (like the fats, oils, and greases we use to make fuels today) is relatively easy to process into valuable fuels. Production costs for biofuels derived from this type of feedstock (HEFA) range from about $4-8/gallon [20], but subsidies make them competitive in certain geographies, and the market is growing. Most of these subsidies place higher value on feedstocks that are reused, like used cooking oil, compared to purpose-grown feedstocks like palm oil, which have questionable environmental benefit. [21] Traditional HEFA feedstock is supply constrained in the absolute (there is not enough to supply a meaningful portion of aviation energy) and in the sense that it has an upward sloping marginal cost curve as supply scales; the most concentrated HEFA feedstock (from densely populated parts of Asia) is the cheapest to collect in bulk, and already dominates global supply. [22]
Other biomass contains comparatively little energy content per tonne, is more widely distributed (and therefore expensive to collect and transport), is expensive to process, or some combination of the above. The conversion of solid biomass via gasification has a long history of failed projects [23] which work on paper when feedstock is free, but rarely in practice, largely because of astronomical capital costs. Converting bioethanol to jet fuel is an emerging route with better prospects [24], but the cheap sources of ethanol are similarly supply constrained and do not always pass the purity tests of regulatory schemes. [25] Next generation ethanol sources that do are structurally more expensive.
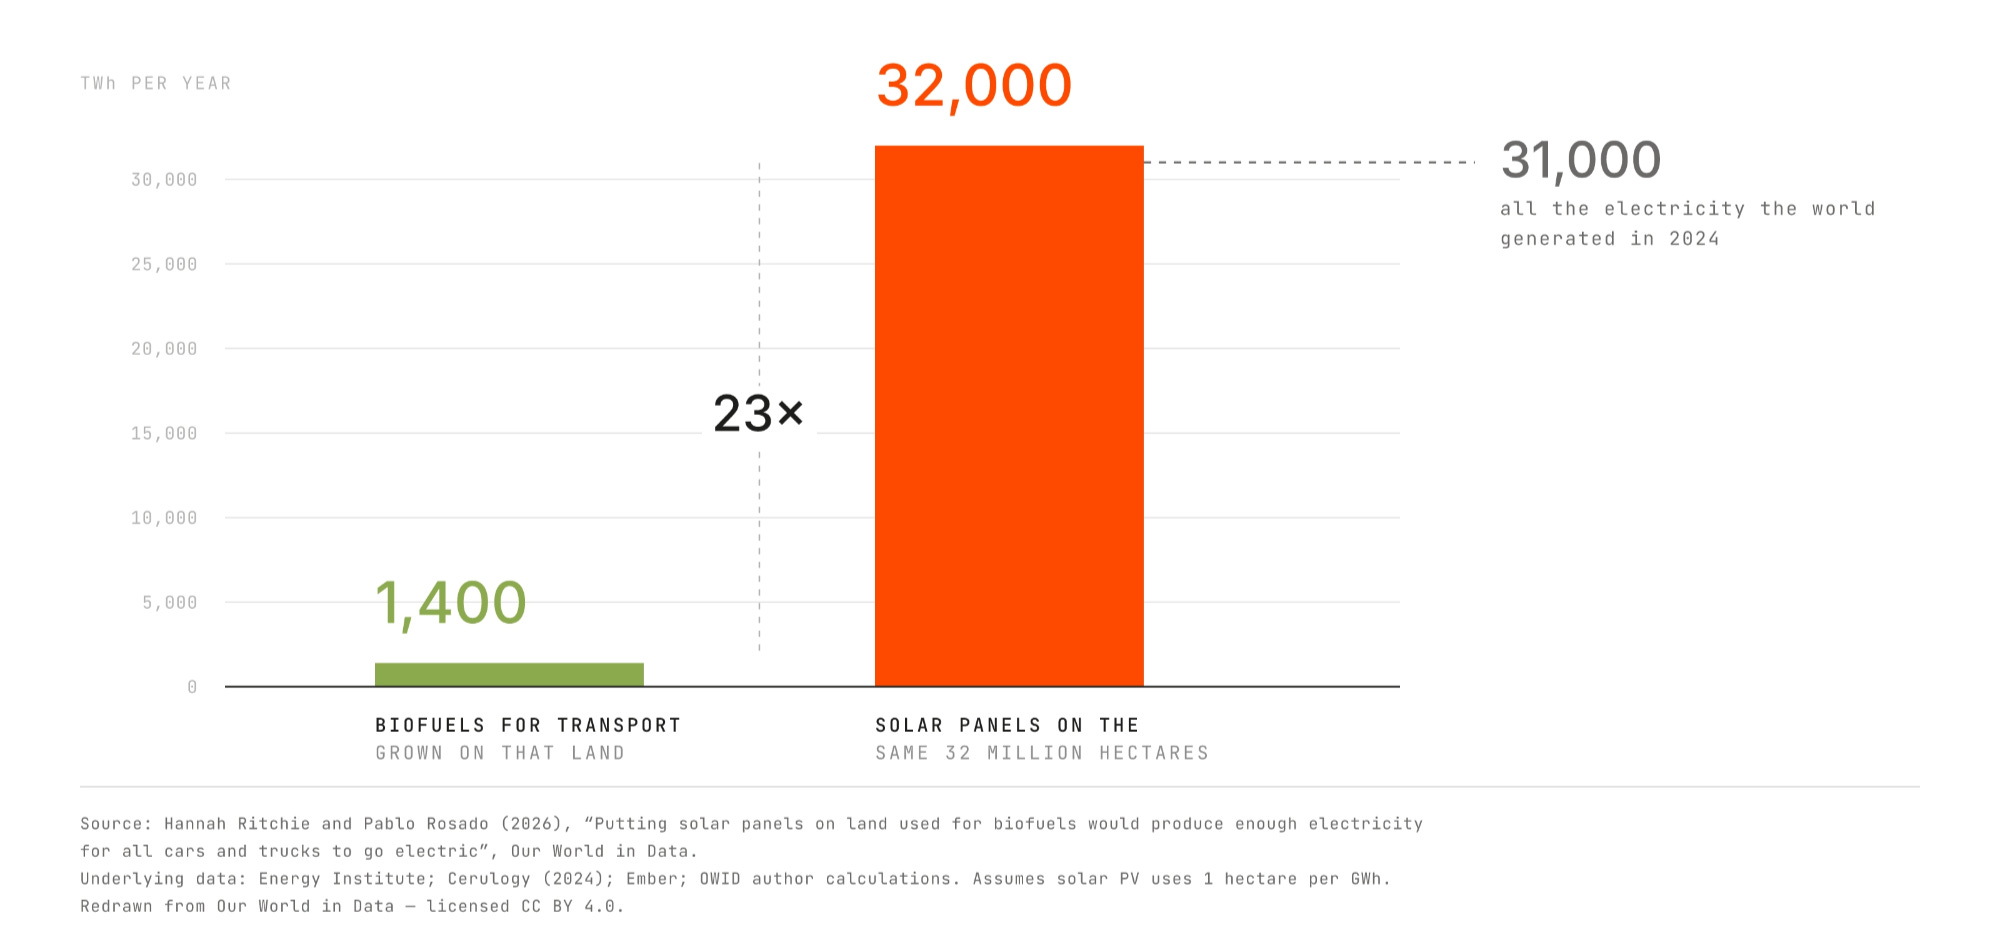
The better argument against getting all our aviation energy from biofuels is their staggering land use. Today’s biofuels occupy an area of land roughly the size of Poland and supply enough energy for just 3-4% of transportation energy demand. [26] The same land area, if occupied with solar panels, would generate more than the world’s entire electricity consumption. [26] Many advocates of biofuels attack the energy consumption of synthetic fuels while conveniently not mentioning the land consumption of biofuels. The irony is that land is actually scarce and limited, while the assumed limits on electricity generation are mostly nonsense, as we discuss below.
But ultimately, it all comes down to cost. Fuel has an energy value in the market. Emissions reductions have value in some markets. Energy security and stable supply chains also carry a value which is priced erratically and perhaps incompletely. Synthetic fuels and biofuels will compete head-to-head to provide those benefits, in places where they have market value, at the lowest possible cost. They may also compete with other solutions like carbon removal (CDR) plus continued fossil use for aviation, if we are OK paying the very high cost associated with converting all of our surviving refineries to only jet-fuel-and-chemical factories. It is, of course, worth noting that the global crude supply and refinery margin curves predict that when we are only making jet and chemicals, these “survivors” are likely to be highly integrated Asian refineries processing mostly Middle East crude, so the CDR pathway is also only of interest if we don’t care about energy security and are perfectly fine being at the mercy of a refined products supply chain which is even more oligopolistic than today’s. For the sake of this argument, we will assume that we care about these second- and third-order effects and that aviation is actually going to develop cost-effective alternative energy sources rather than just waste disposal schemes.
Some would have you believe that it is impossible for synthetic fuels to compete on cost with biofuels. We wouldn’t blame them given some of the early published prices for synthetic fuels, but the notion is easily proven false, as we will show below. Admittedly, actually achieving the conditions required to realize those costs is a matter that requires a significant amount of engineering and remains to be proven. Below we discuss the necessary conditions and how we are achieving them.
Synthetic aviation fuel economics 101
Let’s take a target fuel minimum selling price (MSP) of $4-6/gallon (~$1,300-2,000/tonne) as a baseline for the sake of argument. At that high end of that, a fuel would be directly competitive with HEFA and would have a ~$20 billion, growing market including jet and diesel. [27] At the low end (as we’ve argued above), we think it will eventually compete directly with fossil jet costs, meaning a ~$300-400 billion annual market [28], and there would be a case for higher margins in markets that have any type of environmental or security premium, which constitute a significant majority of global demand. [29]
The minimum selling price of a synthetic jet fuel, MSP, is:
MSP = CapEx + Fixed O&M (FOM) + (CO2 price * CO2 consumption per unit) + (Energy price * Energy consumption per unit)
Where CapEx is an annual figure inclusive of an acceptable risk-adjusted return for a project investor; assume 7.5% over 20 years, which yields a capital recovery factor of 0.098. We will also assume FOM is 4% of Total Installed Cost. Both of these are mature, at scale assumptions, which is by design - we want to look at apples-to-apples cost entitlement, not market entry points.
That reduces the equation to:
MSP = .138 * TIC + (CO2 price * CO2 consumption per unit) + (Energy price * Energy consumption per unit)
Where TIC is expressed in $/Bpd or $/tonne/yr and price is expressed in gallons or tonnes.
Producing jet fuel from CO2 requires a theoretical minimum of ~3.1 tonnes of CO2 per tonne of fuel [30], or about 9.6 kg per gallon. Most processes, including ours, are pretty carbon efficient as most byproducts can be trivially recycled. Let’s say that we’ll need 3.5 tonnes per tonne. CO2 can cost as little as $10-15/ton from ethanol fermentation* or natural gas processing, $50-80/ton from RNG production, and $120-200/ton if captured from a low-partial-pressure stream including any post-combustion capture. [31] All of these assume co-location. Transport via pipeline is a small adder but geographically constraining. Transport via rail, including liquefaction, may cost an extra $40-80/ton. [32] Transport via truck is often cost prohibitive and will be reached for only in desperate cases or where other project advantages are enough to make up the difference. Let’s assume $80/ton as a starting estimate - that contributes just shy of $1/gallon to the cost. This is about what Lydian will pay in its first project.
Jet fuel has about 126-129 MJ per gallon, or 35 -40 kWh (alternatively, for those reading in Europe, 43 GJ or 12 MWh per tonne). [33] Synthetic jet fuel production processes range from about 30% to 50% energy efficiency. [34] Let’s go for a round number near the midpoint - 100 kWh per gallon or 30 MWh per tonne required, about 35-40% efficient. Alternatively, ~1.4-1.5 kg of hydrogen is needed if we prefer to look at hydrogen as an exogenous energy input with a defined cost. [34] Readers will note that the LHV of the hydrogen input is only about 50 kWh/gal [35] and will correctly conclude that the vast majority of energy (and losses) in a synthetic fuels flowsheet will be for hydrogen production (assuming electrolysis is the source). The net reaction of CO2 + H2 → CnHm (hydrocarbons) is exothermic. [36]
A few conclusions fall out almost immediately: first, synthetic fuels are not going to compete directly with biofuels unless they can get electricity around about $30/MWh and/or hydrogen around $2/kg or less. On the other end of the spectrum, even if energy were completely free, the fuel synthesis plant (downstream of electrolysis) needs to cost well under $10,000/tpa. This is not a good sign for many announced European e-SAF projects - several sources claim that early projects are around EUR 1-2B for a 50,000 tpa plant [37], which is 2-4x the target with free energy.
*Ethanol fermentation vents enough CO2 to produce more fuel than all global HEFA refineries (both renewable diesel and SAF) and >10x the amount of HEFA fuel that goes to aviation. [38] In other words, really cheap CO2 is less scarce than HVO/UCO.
What will electricity cost?
Most e-fuels in the foreseeable future will be produced with an electrolyzer integrated onsite, and will think about electricity, not hydrogen, as their input energy.
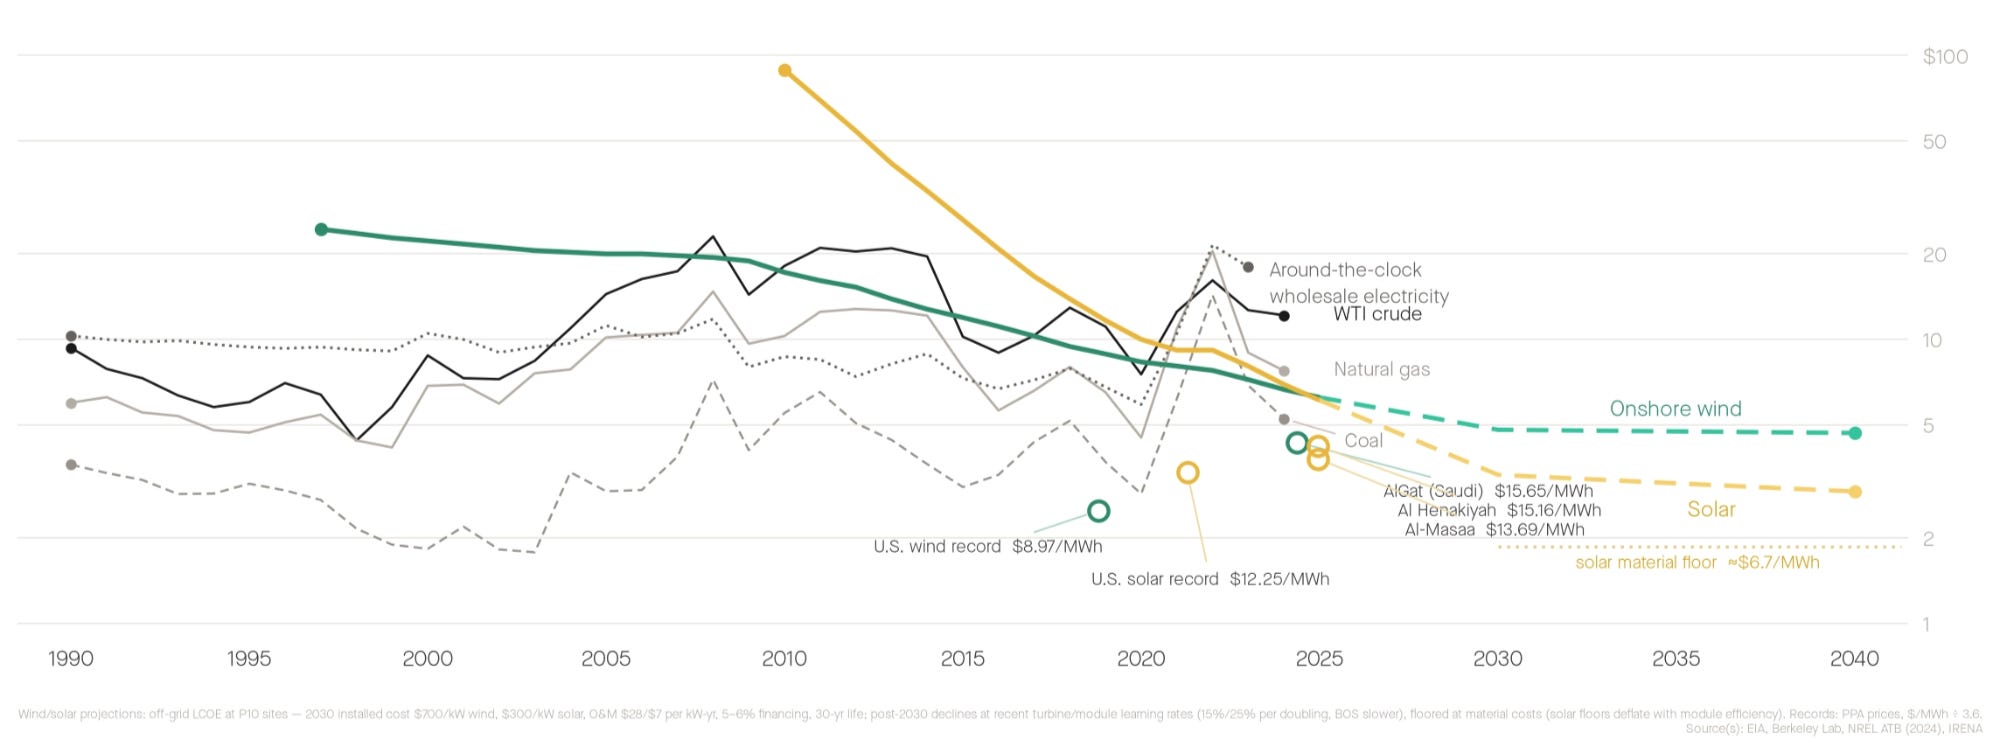
The opportunity for synthetic fuels is the staggering declines in the cost of electricity generation from wind and solar, which are still continuing. Recent wind and solar tenders in the Middle East have come in below $0.02/kWh [39], and previous U.S. records were lower still, though these were supported by tax credits that reduced effective prices by 30-50%. [40] Chinese OEM bids are now around $300/kW for wind equipment and ~$100/kW for solar modules. [41] Including transport and installation but excluding grid costs, levelized energy costs for off-grid projects in top 10 percentile locations could realistically reach ~$10-15/MWh. That would make their energy competitive with global averages for the (primary) energy costs of fossil fuels. This is good, because we need primary energy from solar and wind to be 2-3x lower than primary energy from crude to compete directly with jet fuel. [42] We are just now getting there, and only in the best places in the world.
The original sin of synthetic fuels is to conflate around-the-clock industrial electricity prices with the cost of generation. Industrial electricity prices include much more than generation costs - they also include the cost of capacity (overbuild of the network to achieve a high reliability standard) and deliverability (transmission and distribution wires). These costs are high and going up. [43] Any synthetic fuels project which needs to pay them will not make economic sense.
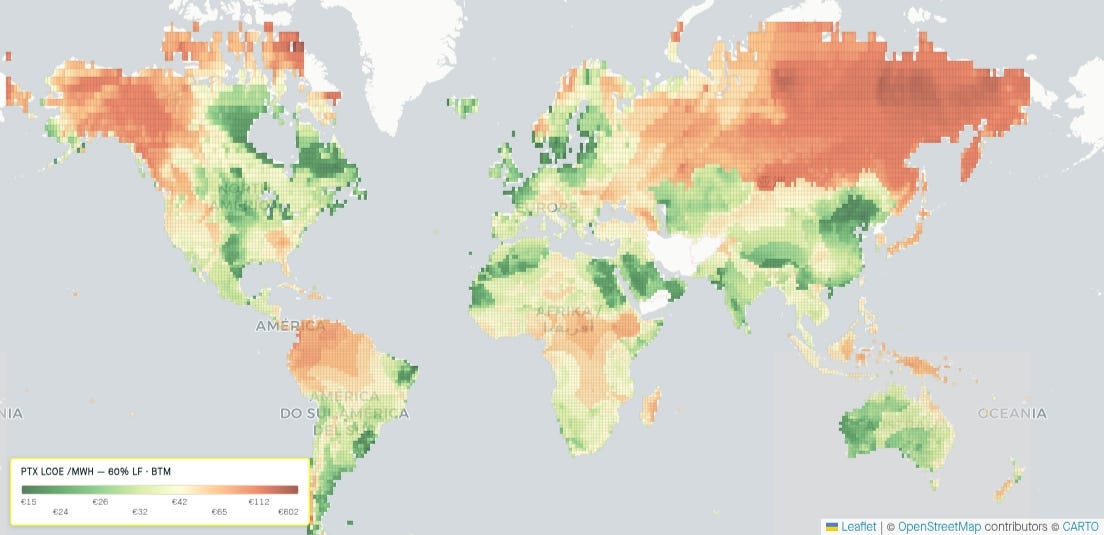
Lydian maintains a proprietary modeling platform called Auriga (the chariot driver) to optimize the design, siting, and operation of its plants. The platform sources both public and private data to estimate solar and wind LCOEs in every location in the world, and then designs and builds the least-cost portfolio for a given target capacity factor. The platform can toggle between grid-tied scenarios, which require higher CapEx for grid connection but also allow the sale of excess electricity, and off-grid cases, which are shown in the below result. This plot uses near-term solar and wind costs with grid connection costs removed and targets a 60% utilization rate. BESS is allowed to be built and is also sized optimally. A turndown floor of 10% is applied because process technologies tend to dislike start/stops even more than they dislike load following. Excess electrons are spilled.
Note: Auriga estimates country-specific installation costs and financing rates but does not yet account for land costs and availability. Construction multipliers are applied for Arctic regions but are based only on port distance and are therefore imperfect for difficult terrains and lack of road access. As a result, Northern Canada (construction difficulty, labor availability), remote Patagonia (same), and coastal Europe (land cost and availability) are certainly optimistic here and should largely be ignored. Tariffs are also not modeled, which makes U.S. results highly optimistic in the near term. Still, significant areas of opportunity remain, mostly in the global South. The best areas may achieve an LCOE at a 60% load factor of just below $0.02/kWh.
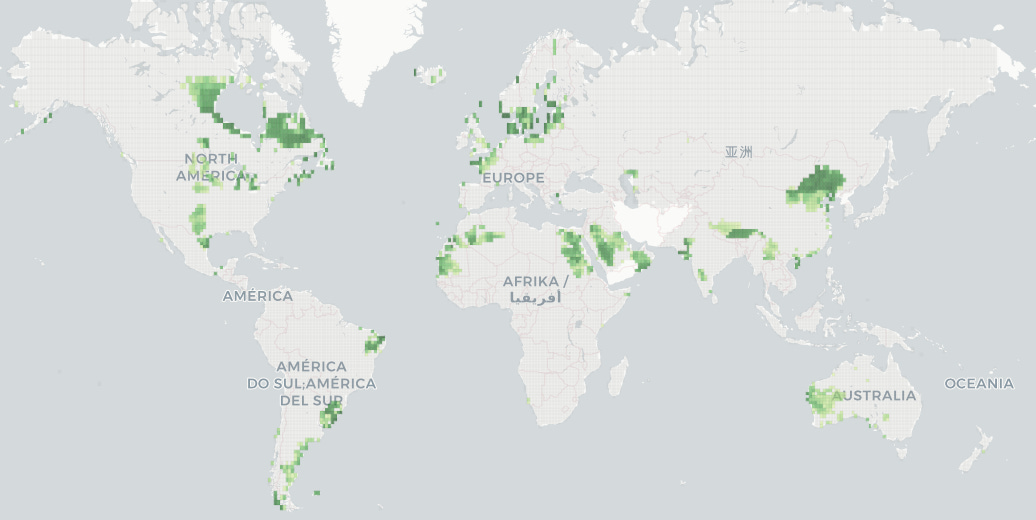
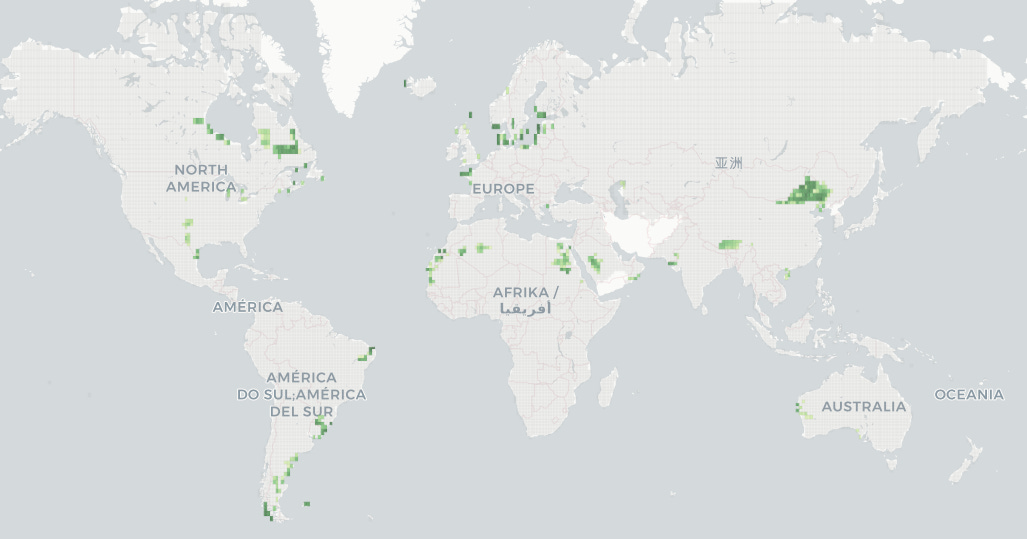
Here is a filtered version of the same run, which shows only the areas where a total energy cost of less than $30/MWh ($0.03/kWh) can be achieved at 60%, 75%, and 90% load factors. You don’t need to squint on the last one - there are no regions in the world where it’s possible and constructible (the lone coastal Patagonia square is likely hard to access and mixing on and offshore wind capacity factors). By comparison, the best off-grid solar-only locations could achieve ~$10/MWh in the near future [44], though this is not Lydian’s design condition (more on this later).
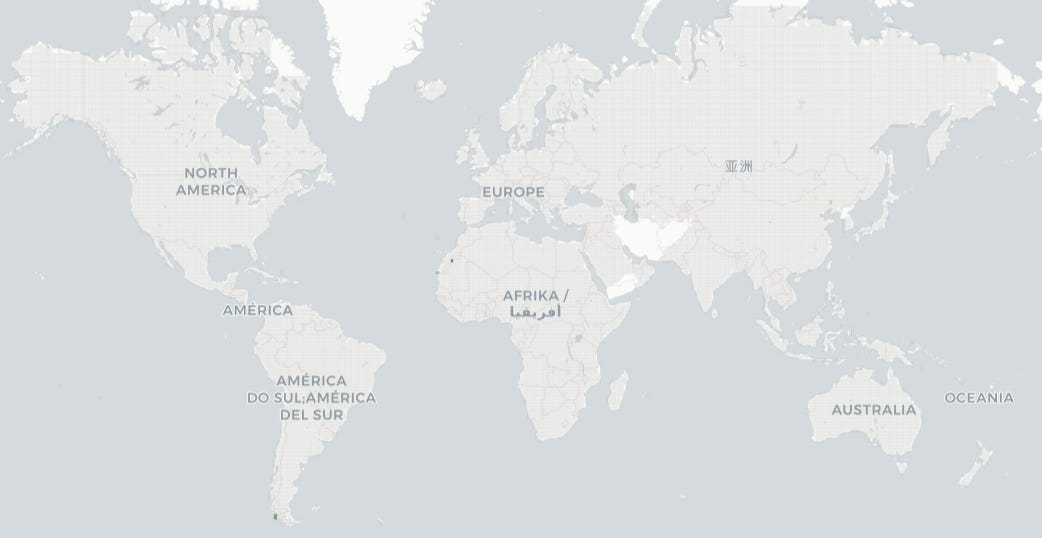
The opportunity cost of renewable electricity for synthetic fuels
Sometimes we run into people who are convinced that wind and solar provide luxuriously cheap energy, but still claim that using it for synthetic fuel production is wrong because it would have a larger climate impact if used to replace fossil generation instead. This is a common argument and it’s not just wrong, it’s completely backwards.
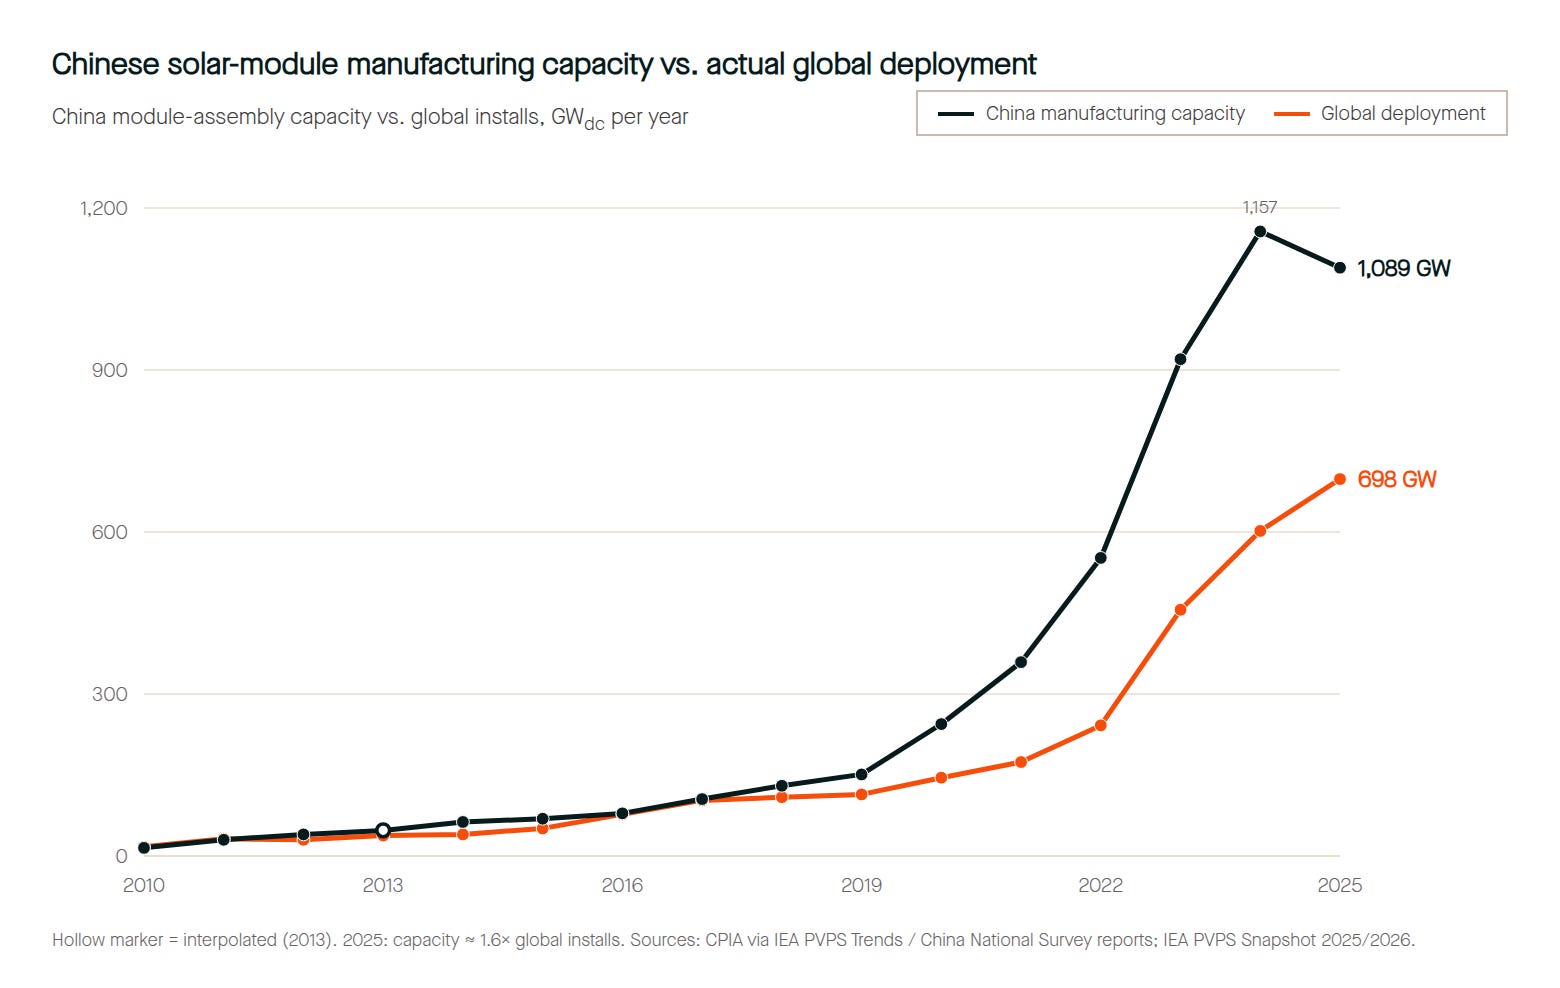
The energy transition is not at risk of wind and solar shortages; on the contrary, it is at risk without more and faster demand for wind and solar, regardless of what it’s used for. In places with significant renewable penetration already, the value of renewable energy is being cannibalized faster than its costs are falling. [45] PV manufacturing capacity is declining for the first time after the end of China’s feed-in tariff in 2025 which has left new generation more exposed to depressed market prices. [46] [47] And grid connection costs and timelines, especially in the West, have skyrocketed. Despite significant demand for new generation, as of the end of 2025, there were ~8,200 projects actively seeking grid interconnection in the U.S., representing 1,312 GW of generation and approximately 749 GW of storage. [48]
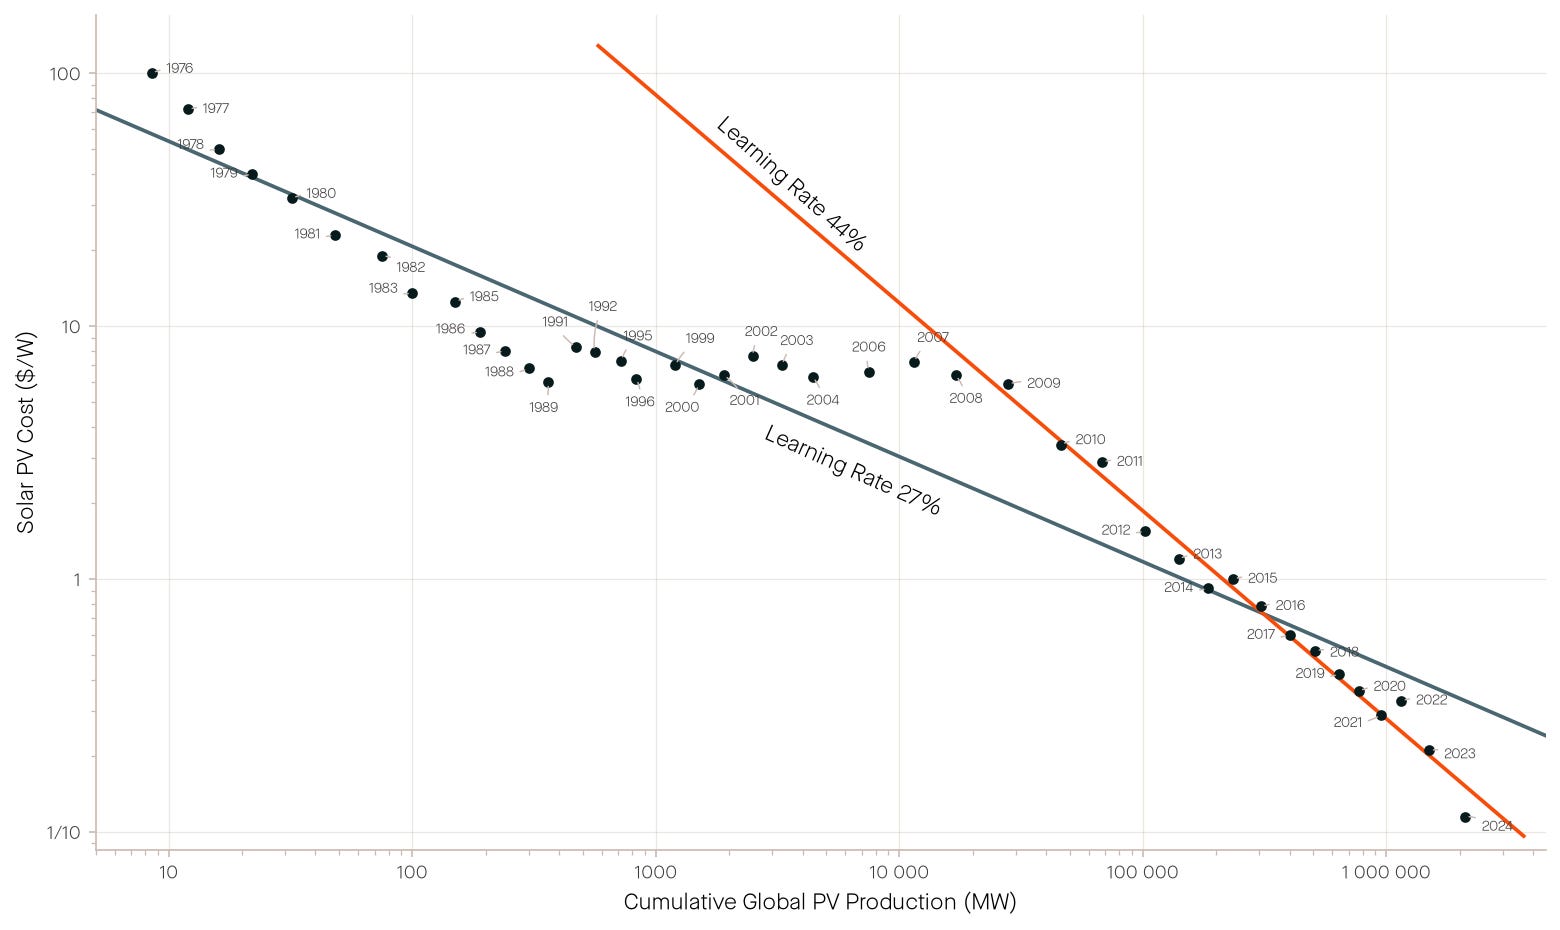
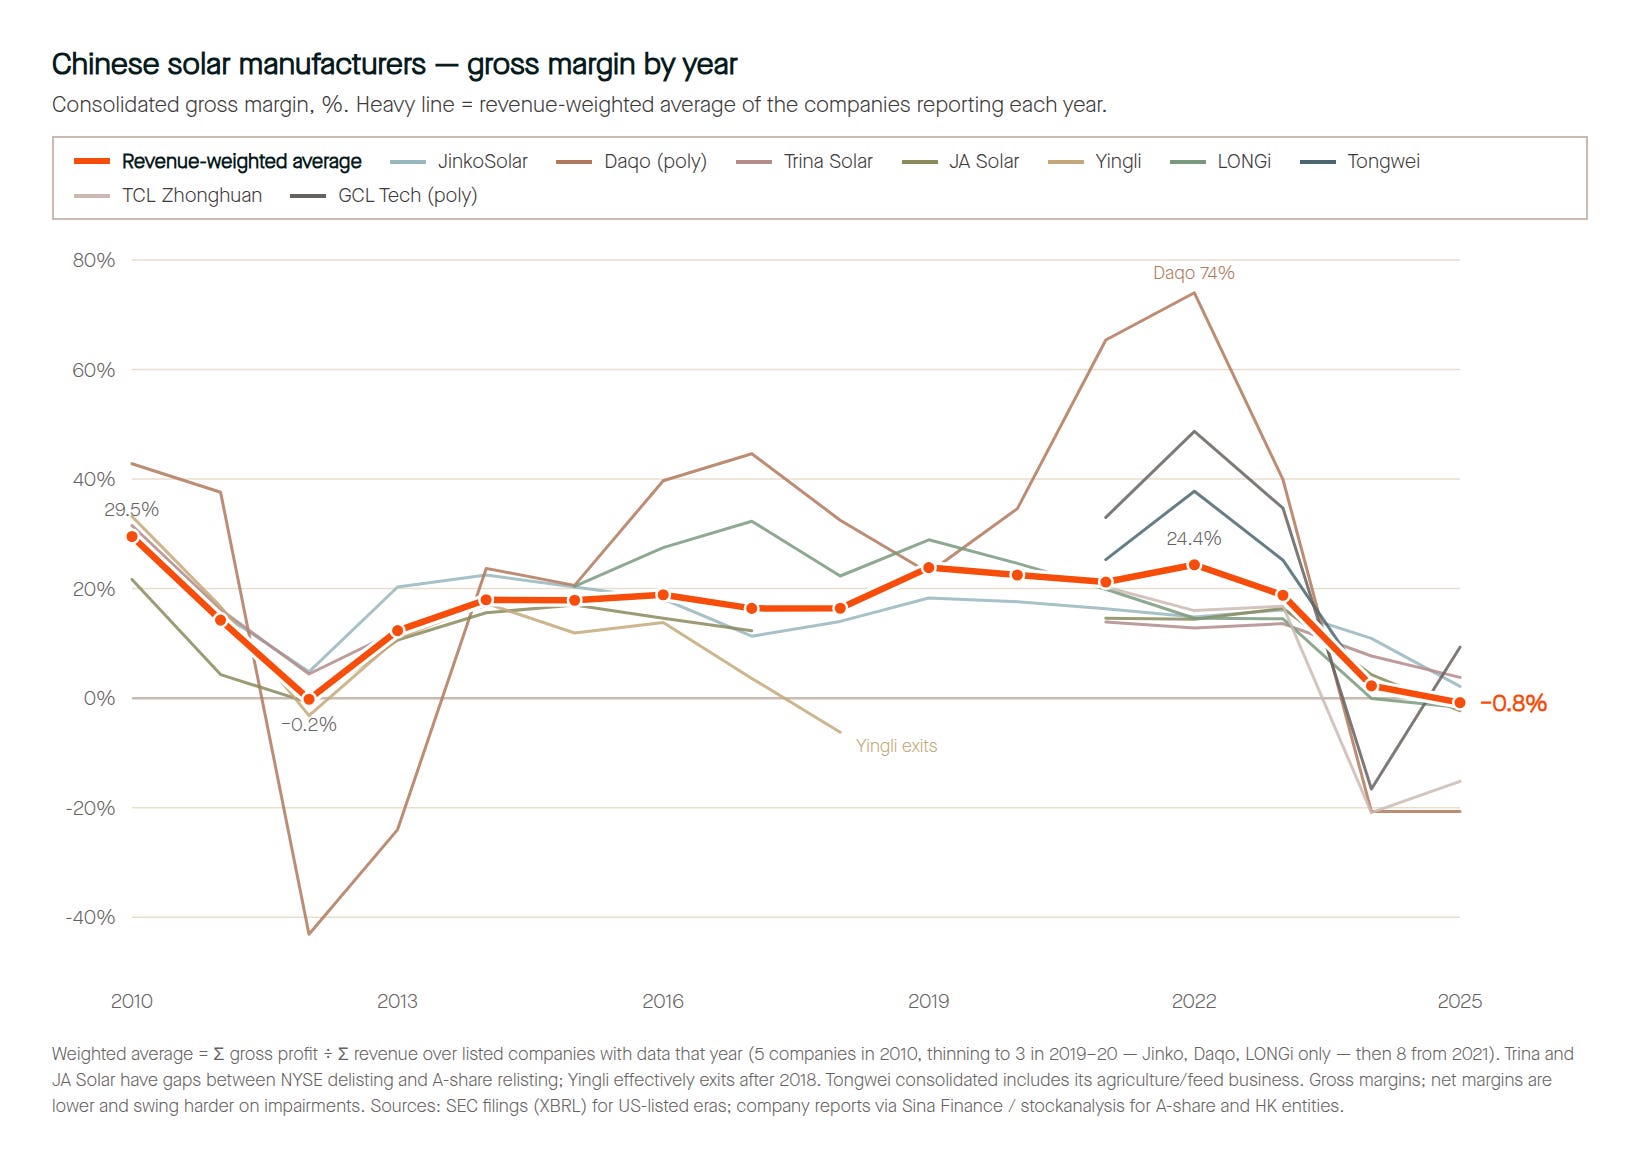
This is a potentially serious problem. Learning rates, despite being often discussed in percentages per year, have cumulative deployments, not time, as the independent variable. Deployment stops, so does learning. And eventually, it reverses: China’s PV manufacturing capacity is now 60% above global deployments and operating at an estimated 30-40% utilization with declining margins. [49] China’s manufacturers cannot keep offering product with low margin forever. If utilization declines, capacity will eventually come offline and costs will increase. Tariffs and other protectionist measures represent another threat. Even the largest announced ambitions for western PV manufacturing remain meager compared to China’s capacity, and are probably at least a decade behind in terms of sophistication, vertical integration, and cost entitlement. [50] If installed costs increase, even last year’s marginally profitable projects will no longer be so, and deployment could stall further, leading us into a negatively reinforcing loop.
In other words, we do not have a shortage of renewable energy - we have a dire need to find more uses for it. And it’s probably better if those uses have nothing to do with the grid, because we seem to have collectively forgotten how to expand that machine at a reasonable rate and cost.
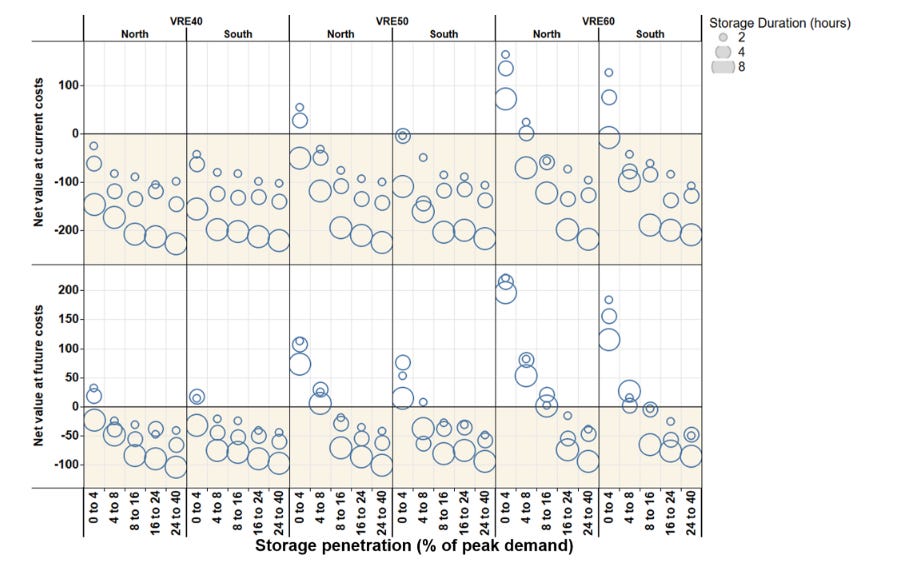
Batteries are not going to save us. Batteries compete with each other for energy arbitrage and grid service revenues, the latter of which saturates incredibly quickly (already mostly gone in ERCOT) [51], and like renewables, they lose their value as more storage is deployed and it becomes unprofitable to deploy further. The economics of battery storage at scale will ultimately depend on capacity substitution; today’s batteries are not very good at providing cost-effective capacity and those that eventually can will do so expensively. With 60% wind and solar penetration, profitable battery deployments will max out at ~10-15% of peak demand even at aggressive future cost targets [52], leaving substantial amounts of energy curtailed. Cheaper renewables also reduce the value of storage, leading to lower deployments and more low- and negative-priced hours.
Flexible loads help a lot more. With sufficiently low capital costs, flexible loads (or “demand sinks”) can achieve >10% of peak load in optimal decarbonized electricity systems and lead to increases in installed wind and solar capacity on the grid by 30-60% while reducing demand for dispatchable generation and without meaningfully impacting battery deployments. [53] Diversity of dispatchable resources also significantly reduces system cost, by which we really mean diversity of capacity substitutes, which can include either generation or demand-side resources. [54] Flexible synthetic fuels plants are excellent capacity substitutes because they are highly sensitive to energy costs and can ramp down indefinitely if there is an economic signal to do so, unlike batteries, which can only discharge for a few hours at a time.
This is why Lydian does not advocate for a strictly off-grid system. We can deploy either on- or off-grid, and we expect that when we grid connect, our assets function as capacity substitutes and do not require additional T&D investment. It is only important that we pay near the cost of generation when wind and solar are available; this means that we deploy in markets which have mechanisms to recognize the value of flexible loads, and that we design our systems with the proper responsiveness and telemetry to function reliably. Put this all together: on grid or off, flexible loads that use tons of energy are extremely good for the energy transition.
China, by the way, realizes this: non-electricity-sector uses of renewable electricity (read: synthetic molecules) are now explicitly stated in the most recent 5-year plan, [55] and 31/31 provinces have established provincial strategies for scaling electrolytic hydrogen in particular. [56] This commitment does not make sense for energy security alone - China has sufficiently cheap coal-derived hydrogen, a strong and growing refining sector, and just showed the world its crude reserves are far larger than we thought [57] - and is better explained as a strategy to also smooth prices on the grid and preserve value for continued domestic wind and solar deployments, thereby keeping manufacturing utilization and exports high.
What will hydrogen cost?
A lot of writing about hydrogen is low-signal. People tend to fall on one end of the spectrum, either still claiming that hydrogen is the “fuel of the future” or taking a little too much schadenfreude in the struggling Western hydrogen market and using current costs and cancelled projects as evidence to claim that electrolytic hydrogen will never be cost effective. While it’s true that the green hydrogen market hasn’t played out as expected in the West, that has proven little except how not to build an electrolysis plant.
BNEF’s hydrogen analysis is an exception. It breaks projects out regionally and by cost bucket to show where costs actually are and indicate what the future might look like for well-executed, at-scale installations. [58] China’s (alkaline) electrolyzer projects at 100 MW+ have reached an average total installed cost of $536/kW as of 2025, more than 4x lower than Western projects. [59] [60] Already at this level, and combined with Inner Mongolian wind and solar costs of ~$0.03/kWh [61] and reasonable O&M assumptions, these projects are likely producing hydrogen intermittently at the plant gate around $2.50/kg. This is consistent with the value reported for Sinopec’s 260 MW Kuqa project [62], and slightly below BNEF’s own estimates, which thinks that China is likely around the $3 threshold, though it’s worth noting that BNEF’s system costs also include storage, which is installed to some extent in many Chinese projects to provide a more stable hydrogen output to downstream consumers. Developers and OEMs privately discuss around $2/kg for projects coming online circa 2028-2030 and for consumers which can accept intermittent output.
Fitting a learning curve off two data points is not exactly best practice, but let’s go ahead. Between 2023 and 2025, China’s installed electrolyzer capacity increased from about 0.8 GW to 2.7 GW [63], or 1.7 doublings, and experienced a 10% cost decline. The implied learning rate is about 6%. China’s recently announced 2030 target is 3 million tonnes per year, or about 35 GW. Many analysts think they may instead achieve 50-80 GW by 2030. [64] If we extend that 6% rate from today’s installed base, TICs may reach ~$400/kW by or around 2030. If China eventually reaches 50 million tonnes of capacity (about half of today’s global market for H2), we could expect system costs to approach $300/kW. With power reaching $0.02/kWh at a 60% load factor, we may see production costs reach ~$1.50/kg, again consistent with BNEF’s long-term estimates.
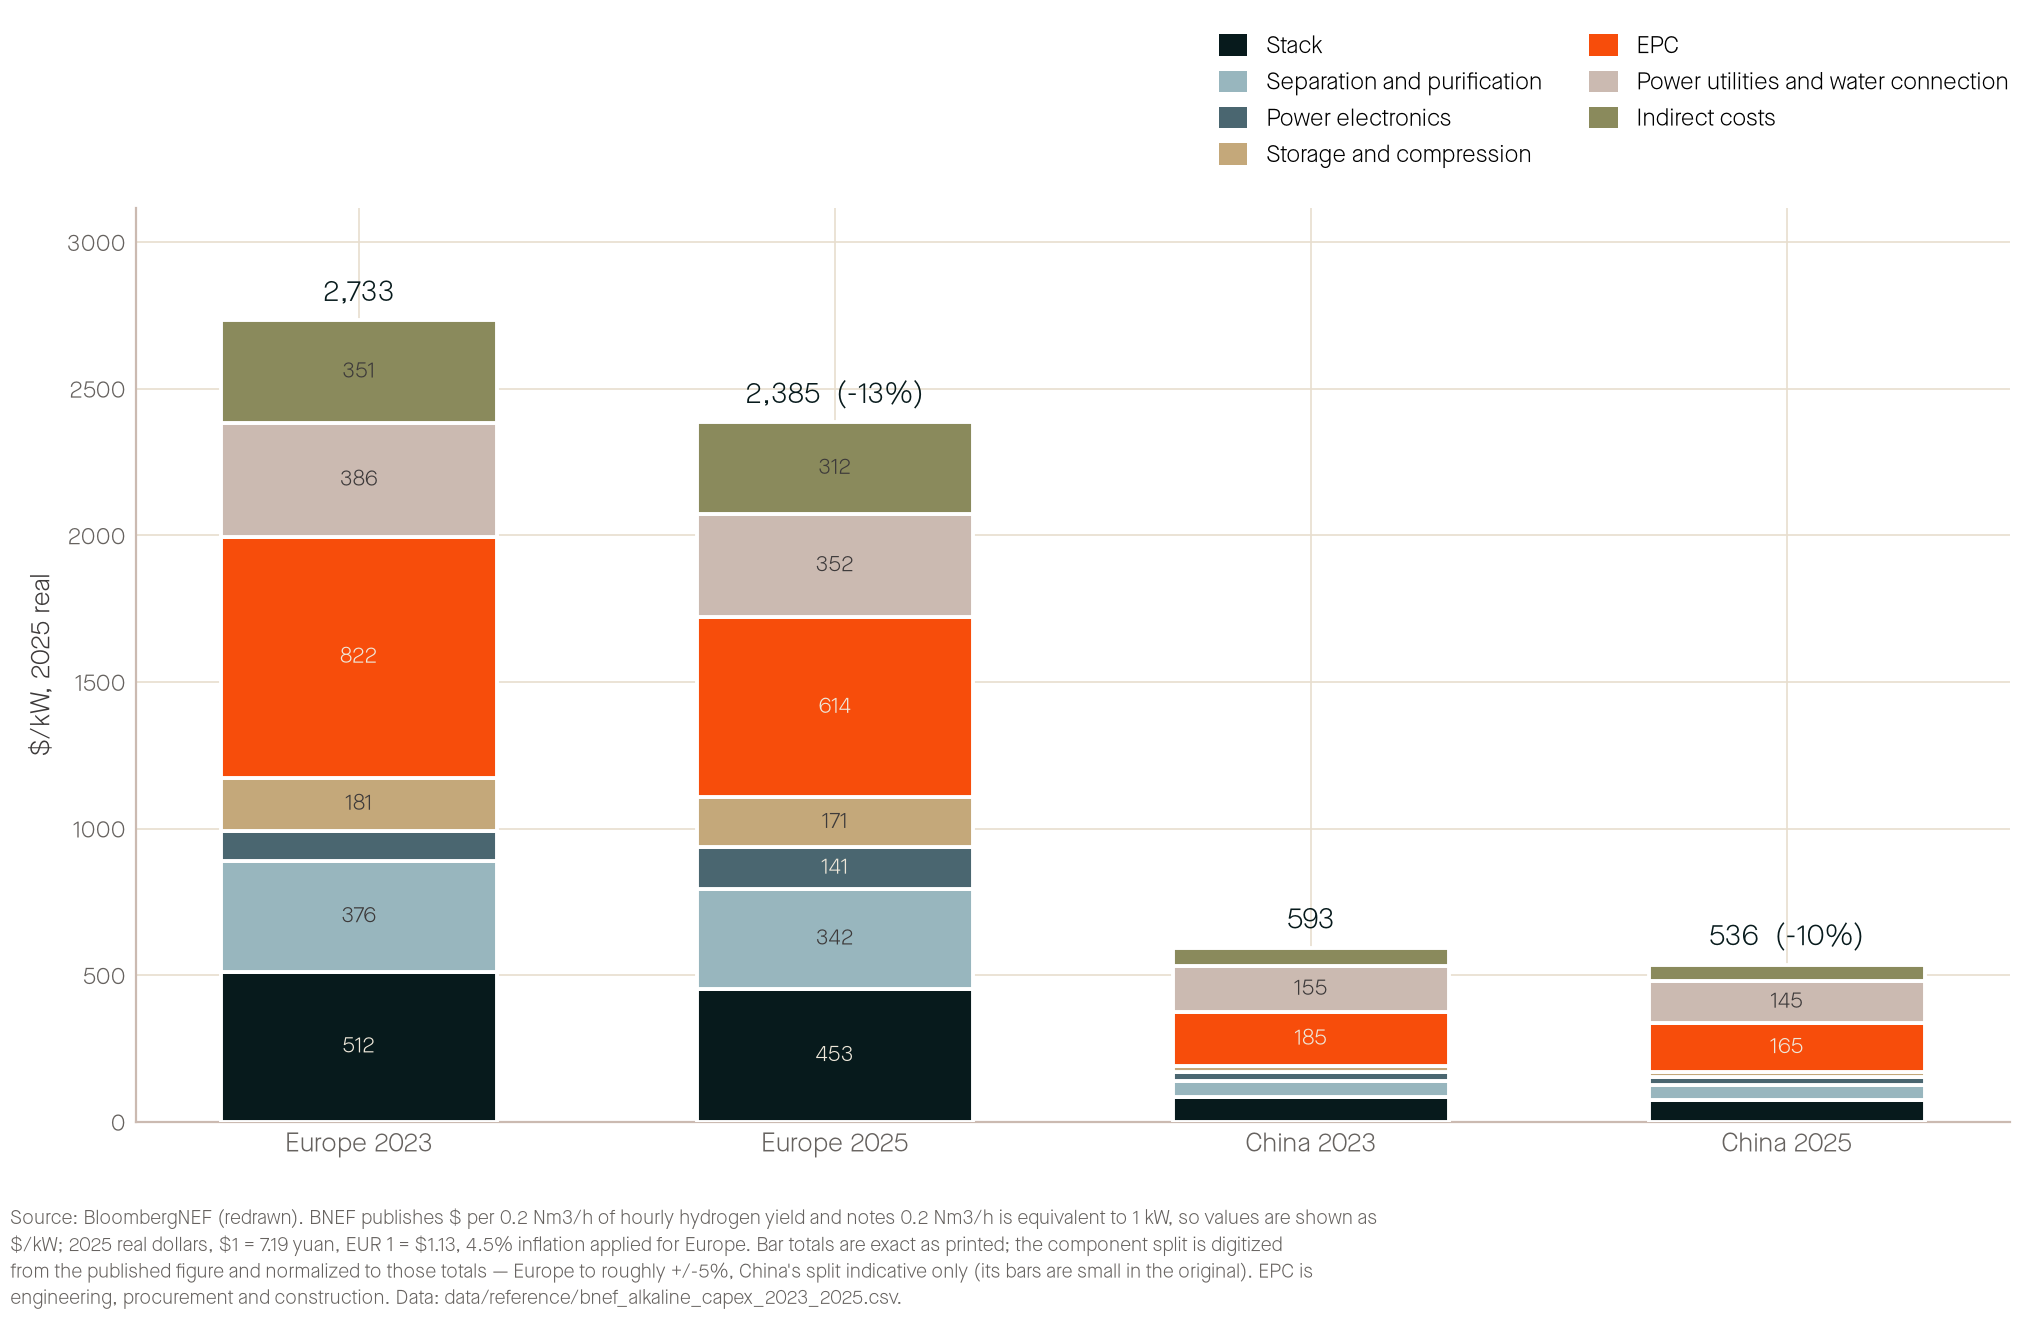
So is something magical about China, or is this replicable elsewhere? It’s true that Chinese stacks are a lot cheaper and, just as in EVs and solar, this comes down to their manufacturing prowess, vertical integration, and willingness to suffer low margins in domestic markets. But any developer can buy Chinese systems at a slight premium. So is it labor? Not really - EPC and owner’s costs for European projects are 4x higher than in China [60] while skilled engineering labor in China is now only at a slight discount to European averages.
The differences are mostly in the delivery model and the resulting cost that the owner bears as a result. In Europe, developers have generally outsourced the supply scope to OEMs who are more or less uninvolved in the plant engineering. The integration scope then goes separately to engineering, procurement, and construction firms (EPCs), usually in the name of “bankability” and experience, though ironically most of them haven’t actually built an electrolysis plant before. These EPCs are far from incompetent, but their incentive structures, competencies, and value proposition make them far better suited to working within established technology scopes and to integrating proven technologies from familiar OEMs that can guarantee the performance of their components. These core competencies have broadly not translated well to novel technologies and riskier OEMs - across geothermal, new nuclear, long duration storage, hydrogen production, renewable fuels, and other technologies, the successful scale-up companies have, almost without exception, invested heavily in in-house engineering teams which can dramatically reduce the EPC scope on their projects.
And this is more or less the model that has taken shape in China, enabled in part by the fact that many of China’s major stack manufacturers have largely grown out of established companies with experience relevant to other parts of plant delivery - LONGi from solar; Sungrow from power electronics and storage; Envision from wind turbines, batteries, energy management software; and Sinopec from refining. [60] This has allowed them to take on considerably more of the system engineering, integration, and delivery scope and risk. The result is a typically a simpler and more holistic system design and a smoother, cheaper, and more replicable delivery model. EPCs are often still engaged on parts of the project scope to which their experience and risk tolerance are better suited.
Western OEMs spent years claiming that cheap Chinese equipment was still more expensive to install once “hidden costs” were accounted for, but these claims didn’t acknowledge that their delivery models were fundamentally flawed. A notable Western exception was Electric Hydrogen, which has for years been advocating for a “whole plant” engineering and delivery model. Now with 100 MW installed, Electric Hydrogen has achieved a TIC that is about half the Western average. [65] The installed cost gaps under this delivery model are no longer deniable nor are they region-specific; in response, Western manufacturers are largely pivoting to more integrated delivery models. It remains to be seen which of them will move fast enough to survive the shakeout, and what TICs can be achieved outside China, but we can safely assume the winners will be closer to Chinese (~$500/kW) than current European (>$2,000/kW) costs. [59]
The hydrogen moonshots
It’s also fun to think about what speculative, step-change opportunities might exist off the more predictable learning and scaling curves of proven electrolysis technologies:
Casey Handmer at Terraform, Austin Vernon, and Harry Hodd at Rivan all write about what ~$1/kg solar-coupled electrolysis could look like. We have enough data at this point to know that this price level is probably unreachable by simply scaling up existing electrolysis technologies, and is dependent on more radical system redesigns that can eliminate much of the stubborn balance of plant scope
There has been a flurry of activity around geologic hydrogen with claimed costs below $1/kg, though nobody has published credible results of commercial flow rates, which could be because there aren’t any or because the information advantage is considered valuable*. Arnout Everts is an expert that publishes well considered analysis with a healthy dose of skepticism
Somewhere in between, some companies aim to produce subsurface hydrogen intentionally and catalytically using pressurized, catalyst-containing brine with costs below $2/kg and broad geographic potential
Other companies, like Molten Industries and Peregrine Hydrogen, make hydrogen as a byproduct of other, more valuable non-energy products, and may achieve very attractive economics as a result, albeit at market sizes which are limited by the main product
*One of my favorite conspiracy theories is that Basque fisherman discovered Newfoundland long before its claimed discovery by John Cabot (and before Columbus reached the New World) and kept the location secret because the cod fishing was just too good. Whether it’s true or not (unlikely), it’s not crazy that the discovery of geologic hydrogen might remain closely guarded until rights are fully secured.
Putting it all together - what does the fuel synthesis plant need to look like?
The energy and feedstock fundamentals for cost-effective synthetic fuels are now in place. What’s required from here is a fuel production technology designed around them. That’s why we founded Lydian in 2021. We realized early on that our technology needed to:
Be as cheap as a refinery, but at much smaller scale. Regardless of how big you would like to build a synthetic fuels plant to achieve scale economies, you will quickly find that the grid connection, land parcel, or hydrogen field to support your plant does not, and will not ever, exist
Be simple. Balance of plant equipment doesn’t get cheaper by learning. It gets cheaper when you make it bigger or when you delete it. We designed our process to operate at extremely high per-pass yields at conditions that are as mild as possible. This required years of catalyst and reactor innovation, but has resulted in a plant that eliminates or massively reduces recycle loops, rotating equipment, and gas separations
Be delivered with an integrated model. We own the engineering of every unit operation and deliver a turnkey process plant. We pay less OEM margin and no licensing fees. We own the integration risk and keep EPC scope limited, well-defined, and repeatable
Load follow gracefully under the intermittency experienced by rapid solar and wind swings. This one is worth an entire blog post of its own, but for now, I like the way Casey puts this: “Most chemical processes do not like intermittency. Tough. [Build] ones that do.” The idea is not to trivialize the challenge of operating a chemical process intermittently; it is to accept, unambiguously, that if you can’t, your unit economics are dead on arrival. Some may tell you “my levelized cost of [hydrogen, fuel production] is actually lower with higher load factors!” - what they really mean is “my plant is so damn expensive that capital recovery dominates my unit economics and I will never produce anything at an affordable price”
In addition to these core principles, the model from the previous sections gave us a clear framework for figuring out exactly where total installed cost needed to land for a high probability success condition with minimal policy support. To us, that meant a clear path to direct competitiveness with HEFA from the first mature projects.
With best-case electrolyzer installed costs in the West, we’d need a TIC for the synthesis plant of ~$75k/Bpd, or just below $2,000/tpa, to compete with biofuels. At today’s Chinese alkaline costs, we have perhaps $50k/Bpd of additional headroom. Further electrolyzer cost reductions, lower CO2 costs, or lower financing costs, and we could compete directly with jet fuel. All of these assume intermittent operation, only a small storage buffer to maintain the plant at 10% minimum load, and locations in the world with optimal wind and solar combinations.
All things considered, though, this is not a very difficult cost target at all. The Dangote refinery recently proposed in Kenya is estimated at $16 billion for 700,000 Bpd [66], or about $23,000/Bpd (~$500/tpa at jet fuel density). We’ll never build synthetic fuel plants at that scale, but even at 1/100th the size and with a scaling factor of 0.6, the unit cost would be <$150,000/Bpd (~$3,000/tpa). And this is for a refinery with a Nelson complexity significantly higher than US or European refinery averages. [67] We can and should build synthetic fuels plants much simpler and cheaper.
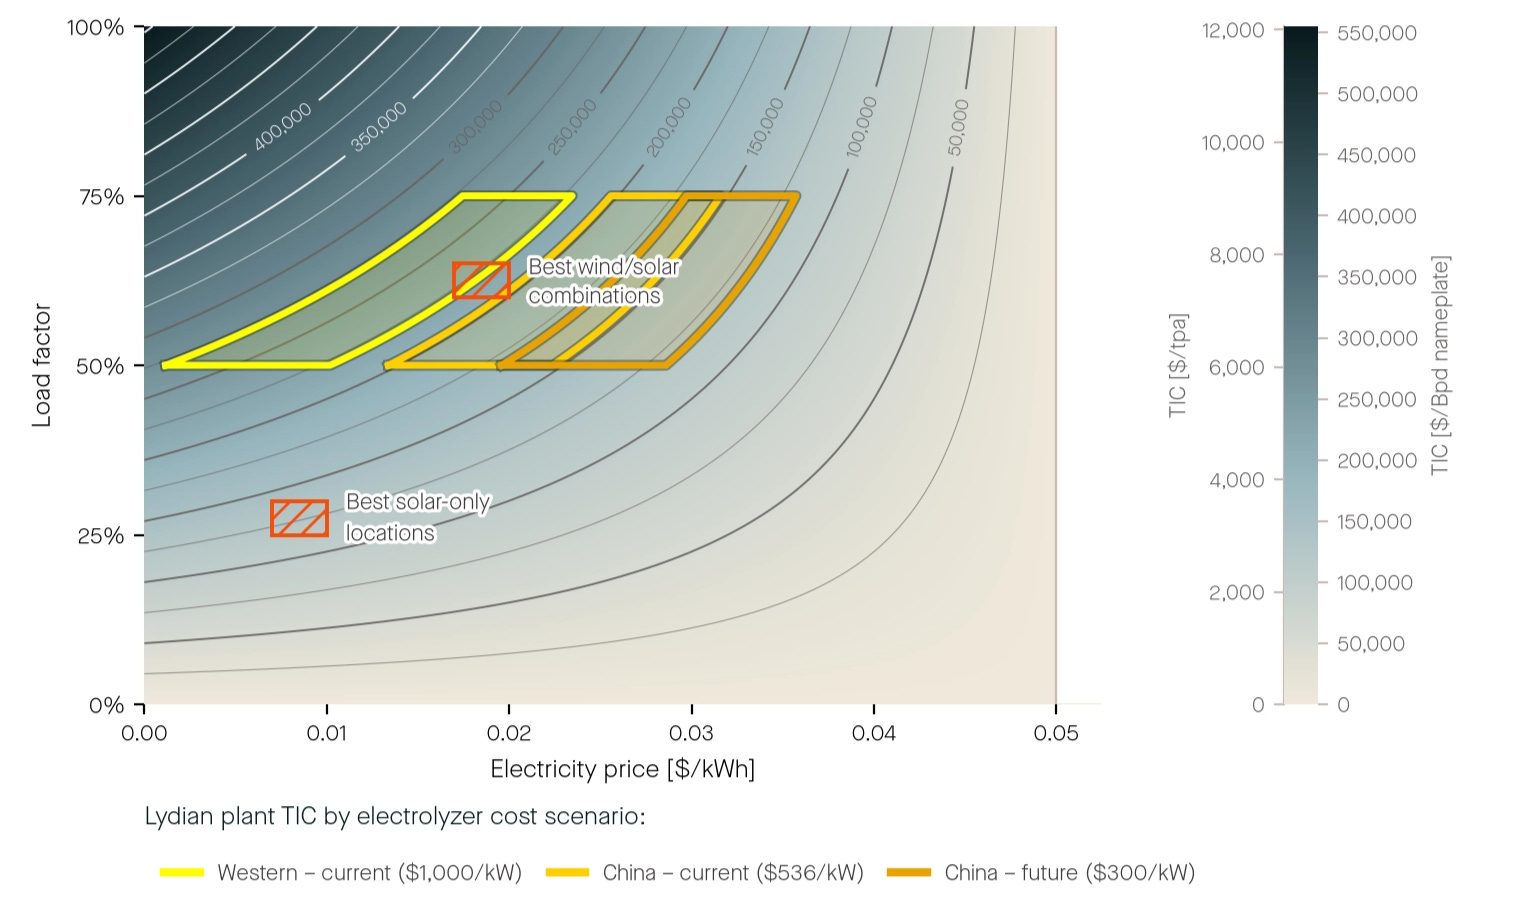
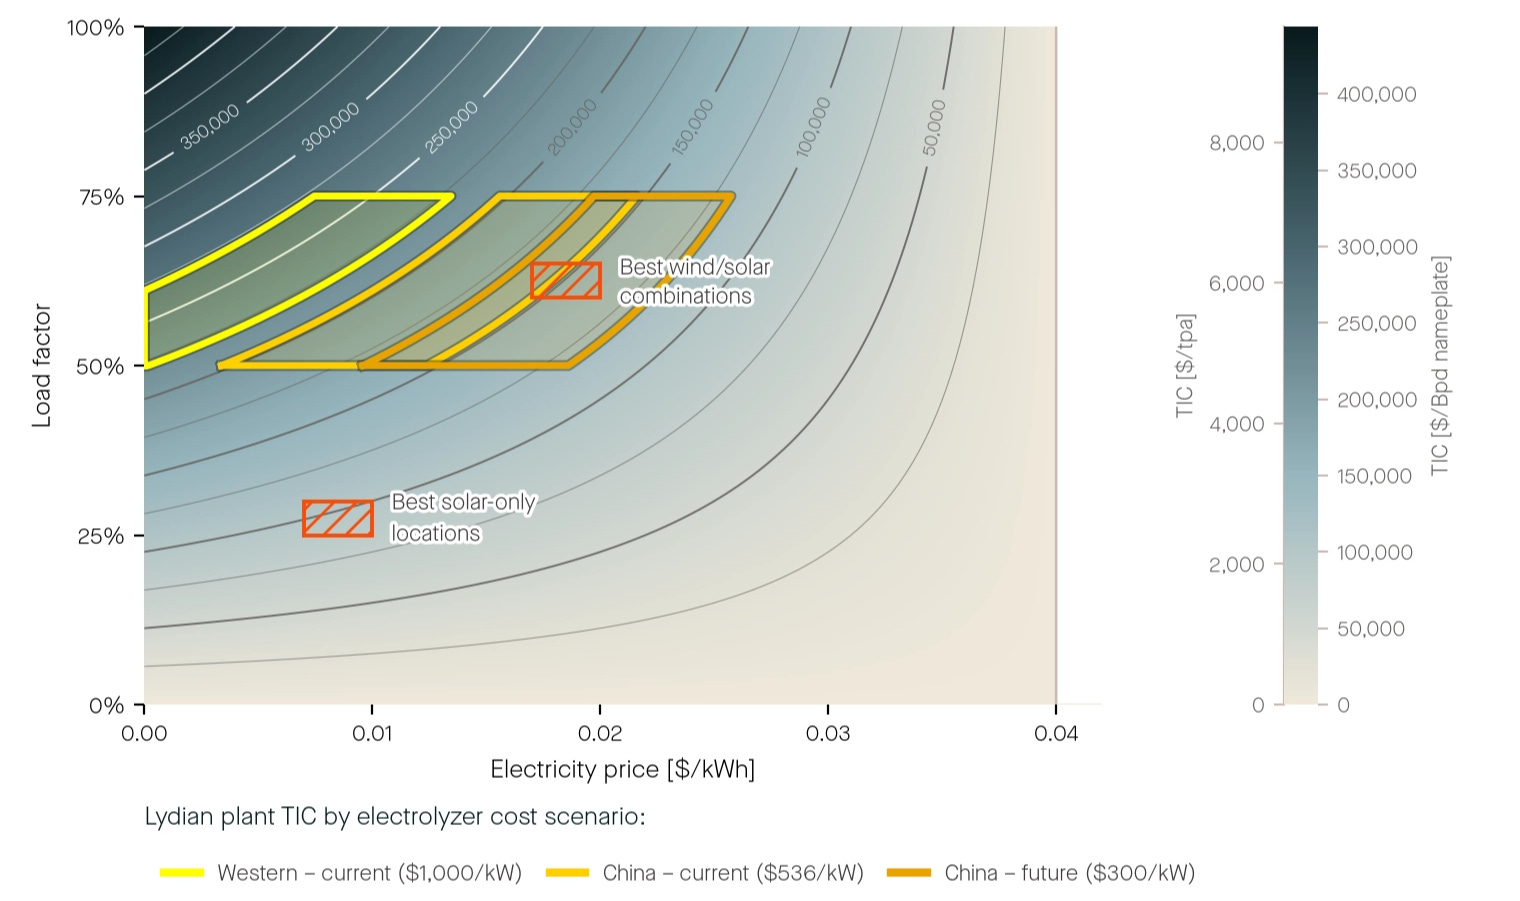
We also need to be realistic about how, and how much, our process could get cheaper over time. There is a lot of magical thinking about the cost-down trajectories of synthetic fuels plants - some have even been misguided enough to overlay solar or battery learning rates. But most process technologies experience only modest cost improvement, much of which comes from scale rather than learning. [68] We do have certain components in our system that are novel and will get much cheaper as we scale up manufacturing, so we use a multi-factor model that incorporates realistic and literature-anchored learning rates for each part of the plant. We expect the total cost of the synthesis plant to come down by ~40% over time, and we hope that much of that will be realized between the first and second plant. We spent a ton of time understanding what made up the cost of synthetic fuel plants, including built examples of the predecessor technology, gas-to-liquids, to figure out where cost could be reduced. [69]
After about a year, we had lots of ideas for how to build a plant that would considerably reduce costs and early prototypes that indicated it could work. We became convinced that a long-term synthesis TIC of ~$75k/Bpd excluding electrolysis was possible, with a first of a kind cost around ~$125k/Bpd. These TIC targets led us to target the best wind and solar combinations rather than solar only - for a complex molecule like jet fuel, a higher degree of process complexity and associated CapEx appears unavoidable without significant R&D advancement; the headroom offered by a 50-75% load factor will be valuable. At our long term targets, direct PV-coupled production may become eventually feasible in very low cost hydrogen scenarios, but those remain speculative.
We eventually called our technology PIVOT, and officially launched the product last month. It’s a turnkey plant that converts CO2 and hydrogen to jet fuel. We’ve demonstrated the technology at the pilot scale already and will be deploying our first full-scale PIVOT modules in the next 2 years in Texas. Most of the system is already designed and quoted, and we’re proud to report that the cost of this first plant will be within striking distance of our targets, not a multiple higher.
We will be writing more about PIVOT and how it works soon.
If you’re interested in connecting, please reach out at info@lydianlabs.com
References
International Energy Agency, “Trends in Electric Cars,” Global EV Outlook 2026, May 2026.
ECG – The Association of European Vehicle Logistics, “Volume of New Vehicle Exports from China – H1 2026 Update” (CAAM data), July 2026.
U.S. Bureau of Economic Analysis, “Auto Exports (AUENSA), Supplemental Estimates – Motor Vehicles,” via FRED, Federal Reserve Bank of St. Louis, July 2026.
International Energy Agency, “Electric Vehicle Charging,” Global EV Outlook 2026, May 2026.
Howe, C. and Li, S., “China Sets Sights on Heavy Truck Electrification in Blow to Diesel Demand,” Reuters, 2026.
Kim, H.J., Shrestha, S. and Pranawengkapti, K., “Capacity and Market Potential for Local Production and Distribution of Electric Two-Wheelers in Southeast Asia, Focused on Thailand, Indonesia and Vietnam,” Sustainable Earth Reviews 8:3, February 2025.
U.S. Energy Information Administration, “How Much Gasoline Does the United States Consume?” (FAQ), March 2024; and “Increasing Fuel Efficiency Leads to Decreasing Gasoline Consumption,” Today in Energy, April 2026.
International Energy Agency, Oil 2025, June 2025; and Perkins, R., “Commodities 2025: Global Fuel Markets Diverge as Road Demand Peaks, Jet Climbs,” S&P Global Commodity Insights, December 2024.
International Energy Agency, Oil 2025, June 2025 (petrochemical feedstock share); and “Road Transport Fuels,” Sheltering From Oil Shocks, March 2026.
Gelder, A., Sehmi Singh, A. and Gaonkar, A., “Global Refinery Closure Outlook to 2035,” Wood Mackenzie, March 2025.
American Fuel & Petrochemical Manufacturers, “Refining Capacity 101: What to Understand Before Demanding ‘Restarts’,” AFPM, June 2022.
U.S. Energy Information Administration, “U.S. Refining Capacity Decreased During 2025,” Today in Energy, June 2026.
Gössling, S. and Humpe, A., “The Global Scale, Distribution and Growth of Aviation: Implications for Climate Change,” Global Environmental Change 65, November 2020.
Bukold, S., “Jet Fuel Demand and Air Traffic (December 2025 Update),” EnergyComment, December 2025, reporting BloombergNEF and IEA projections; and U.S. Energy Information Administration, International Energy Outlook.
U.S. Energy Information Administration, “Refinery Yield of Kerosene-Type Jet Fuel,” Petroleum & Other Liquids, 2026; and International Air Transport Association, “Conventional Aviation Fuel and the Energy Transition: Refineries in Focus,” May 2025.
U.S. Energy Information Administration, “U.S. Jet Fuel Production Rises After Prices Doubled in March,” Today in Energy, June 2026.
U.S. Energy Information Administration, “Gulf Coast (PADD 3) Refinery Yield of Kerosene-Type Jet Fuel, Monthly,” Petroleum & Other Liquids, August 2026.
U.S. Energy Information Administration, “U.S. Gulf Coast Kerosene-Type Jet Fuel Spot Price FOB, Monthly,” Petroleum & Other Liquids, August 2026.
Ritchie, H. and Rosado, P., “Could Biofuels Meet Demand for Global Aviation?,” Our World in Data, 2026.
Rosales Calderon, O. et al., “Sustainable Aviation Fuel State-of-Industry Report: Hydroprocessed Esters and Fatty Acids Pathway,” NREL/TP-5100-87803, National Renewable Energy Laboratory, July 2024.
European Commission, “Commission Delegated Regulation (EU) 2019/807 Regarding the Determination of High Indirect Land-Use Change-Risk Feedstock,” Official Journal of the European Union, March 2019.
S&P Global Commodity Insights, “China Data: 2024 UCO Exports Hit All-Time High on Demand from US, EU, Singapore,” February 2025.
Mesfun, S.A., “Biomass to Liquids (BtL) via Fischer-Tropsch: A Brief Review,” ETIP Bioenergy Factsheet, RISE, 2021 (updated 2022).
Uddin, M.M. et al., “Sustainable Aviation Fuel from Ethanol: Techno-Economic Analysis and Life Cycle Analysis,” Applied Energy 398:126373, July 2025.
European Parliament and Council, “Regulation (EU) 2023/2405 on Ensuring a Level Playing Field for Sustainable Air Transport (ReFuelEU Aviation),” Official Journal of the European Union, October 2023.
Ritchie, H. and Rosado, P., “Putting Solar Panels on Land Used for Biofuels Would Produce Enough Electricity for All Cars and Trucks to Go Electric,” Our World in Data, 2026.
IEA Bioenergy Task 39 (van Dyk, S., Su, J. and Saddler, J.), “Update on Drop-in Biofuel and Co-processing Commercialization,” IEA Bioenergy, June 2024; and International Air Transport Association, “Fuel Fact Sheet,” IATA, June 2026. (Market value is an estimate derived from published volumes and prices, not a single published figure.)
International Air Transport Association, “Middle East Disruptions and High Fuel Prices Halve Airline Industry Profitability,” IATA Press Release, June 2026.
International Air Transport Association, “Fact Sheet – CORSIA,” IATA, June 2026.
Concawe, “Role of E-Fuels in the European Transport System – Literature Review,” Report 14/19, January 2020.
Baylin-Stern, A. and Berghout, N., “Is Carbon Capture Too Expensive?,” IEA Commentary, February 2021; and International Energy Agency, “The Role of E-Fuels in Decarbonising Transport,” December 2023.
Stolaroff, J.K. et al., “Transport Cost for Carbon Removal Projects with Biomass and CO2 Storage,” Frontiers in Energy Research, May 2021.
U.S. Energy Information Administration, “Appendix A: British Thermal Unit Conversion Factors, Table A1 — Approximate Heat Content of Petroleum and Biofuels,” Monthly Energy Review, 2026.
Batteiger, V., Ebner, K., Habersetzer, A., Moser, L., Schmidt, P., Weindorf, W. and Rakscha, T., “Power-to-Liquids: A Scalable and Sustainable Fuel Supply Perspective for Aviation,” German Environment Agency (Umweltbundesamt), January 2022.
U.S. Department of Energy, Hydrogen and Fuel Cell Technologies Office, “DOE Technical Targets for Onboard Hydrogen Storage for Light-Duty Vehicles,” U.S. Department of Energy; and Oak Ridge National Laboratory, “Lower and Higher Heating Values of Gas, Liquid and Solid Fuels,” Biomass Energy Data Book, ORNL (GREET data).
Ye, R.-P., Ding, J., Gong, W., Argyle, M.D., Zhong, Q., Wang, Y., Russell, C.K., Xu, Z., Russell, A.G., Li, Q., Fan, M. and Yao, Y.-G., “CO2 Hydrogenation to High-Value Products via Heterogeneous Catalysis,” Nature Communications 10:5698, December 2019.
Transport & Environment, “The E-SAF Market: Europe’s Head Start and the Road Ahead,” T&E SAF Observatory, 2025.
Irwin, S., “CO2 Production by the U.S. Ethanol Industry and the Potential Value of Sequestration,” farmdoc daily 14(34), University of Illinois, February 2024; and Renewable Fuels Association, “Annual World Fuel Ethanol Production,” 2026.
Jowett, P., “Saudi Arabia Awards 3 GW of Solar in Sixth Renewables Tender Round,” pv magazine International, October 2025.
Seel, J., Mulvaney Kemp, J., Cheyette, A., Gorman, W., Darghouth, N., Robson, D., Rand, J. and Jeong, S., “U.S. Utility-Scale Solar — 2025 Data Update,” Lawrence Berkeley National Laboratory, October 2025.
Yicai Global, “Wind Power Bids Double Year-on-Year as Turbine Prices Rebound,” Yicai Global, April 2025; and InfoLink Consulting, “PV Spot Price,” InfoLink, August 2026.
U.S. Energy Information Administration, “Short-Term Energy Outlook, Table 2: Energy Prices,” EIA, August 2026; and “Approximate Heat Content of Petroleum and Natural Gas Plant Liquids,” Annual Energy Review, EIA. (Per-MWh figures are derived from published prices and heat contents.)
Wiser, R., Barbose, G., Gorman, W., O’Shaughnessy, E., Forrester, S., Donohoo-Vallett, P., Cappers, P., Deason, J., Hledik, R. and Lam, L., “Retail Electricity Price Trends and Drivers: Data Update — 2026 Edition,” Lawrence Berkeley National Laboratory, April 2026.
Jowett, P., “Solar LCOE to Fall 30% by 2035, Says BloombergNEF,” pv magazine USA, February 2026; and IRENA, Renewable Power Generation Costs in 2024, July 2025.
Franke, A. and Grama, M., “Deflating Capture Prices Pull Solar, Wind Market Values Down Across Europe in 2024,” S&P Global Commodity Insights, January 2025.
Davidson, M. and Qian, J., “China’s Solar Industry Is in Upheaval—The Effects Will Be Global,” Center for Strategic and International Studies, 2026.
Xiao, C., “Chinese Polysilicon Production Has Recorded Its First Decline in 12 Years – CPIA,” PV Tech, December 2025.
Rand, J., Cheyette, A., Talley, C., Zhang, S., Gorman, W., Wiser, R.H., Seel, J., Jeong, S. and Kahrl, F., “Queued Up: 2026 Edition — Characteristics of Power Plants Seeking Transmission Interconnection as of the End of 2025,” Lawrence Berkeley National Laboratory, May 2026.
InfoLink Consulting, “Solar PV Supply Chain: 2026 Marks the Industry Trough and the Beginning of Restructuring,” February 2026.
IEA, “Energy Technology Manufacturing and Trade,” Energy Technology Perspectives 2026, International Energy Agency, March 2026; and Fraunhofer ISE, “Photovoltaics Report,” Fraunhofer ISE, July 2026.
Vermillion, B., “ERCOT: Are Ancillary Services Now Saturated with Battery Energy Storage?,” Modo Energy, October 2024.
Mallapragada, D.S., Sepulveda, N.A. and Jenkins, J.D., “Long-Run System Value of Battery Energy Storage in Future Grids with Increasing Wind and Solar Generation,” Applied Energy 275:115390, October 2020.
van der Jagt, S., Patankar, N. and Jenkins, J.D., “Understanding the Role and Design Space of Demand Sinks in Low-Carbon Power Systems,” Energy and Climate Change 5:100132, 2024.
Baik, E., Chawla, K.P., Jenkins, J.D., Kolster, C., Patankar, N.S., Olson, A., Benson, S.M. and Long, J.C.S., “What Is Different About Different Net-Zero Carbon Electricity Systems?,” Energy and Climate Change 2:100046, 2021.
Atchison, J., “China’s 15th Five-Year Plan: New Details on National Hydrogen, Ammonia Ambitions,” Ammonia Energy Association, August 2026.
Hydrogen Insight, “Analysis: How All 31 Mainland Chinese Provinces Plan to Grow Their Hydrogen Sectors, According to Their New Five-Year Plans,” June 2026.
Ministry of Natural Resources of the People’s Republic of China, “225 Large, Medium-Sized Crude Oil and Natural Gas Fields Discovered from 2021 to 2025,” reported in Global Times, April 2026.
BloombergNEF, Hydrogen Levelized Cost Update, BNEF, 2024–2025.
International Energy Agency, Global Hydrogen Review 2025, October 2025.
Gielen, D. and Lopez Rocha, C. (eds.), “Electrolyzers for Hydrogen Production: Technical and Economic Characteristics,” World Bank Group / ESMAP, February 2026.
International Renewable Energy Agency, Renewable Power Generation Costs in 2024, July 2025.
Zhao, T., “Hydrogen Case Study: Operational Efficiency and Electrolyser Technology at the Sinopec Kuqa Project,” Wood Mackenzie, August 2024.
International Energy Agency, Global Hydrogen Review 2024, September 2024.
Hydrogen Insight, “China Vows to Install Two Million Tonnes of Annual Green Hydrogen Production by 2030 in New National Strategy,” June 2026; and “China’s Green Hydrogen Production Expected to Surpass Three Million Tonnes in 2030, Says Former Senior Official,” October 2025.
St. John, J., “Green Hydrogen Hype Has Dried Up. This US Startup Is Pressing On,” Canary Media, February 2026.
Gachie, K., “Dangote-Backed Lamu Oil Refinery Set to Begin Construction in October 2026,” Citizen Digital, August 2026.
Williams, K., “Advantages of Complexity Index Design of Dangote Refinery,” P.M. News Nigeria, January 2023, citing Maples, R.E., Petroleum Refinery Process Economics, 2nd ed., 2000.
Rubin, E.S., Azevedo, I.M.L., Jaramillo, P. and Yeh, S., “A Review of Learning Rates for Electricity Supply Technologies,” Energy Policy 86, August 2015; and Way, R., Ives, M.C., Mealy, P. and Farmer, J.D., “Empirically Grounded Technology Forecasts and the Energy Transition,” Joule 6(9), September 2022.
Glebova, O., “Gas to Liquids: Historical Development and Future Prospects,” Oxford Institute for Energy Studies, Paper NG 80, December 2013.

This is a great forward looking analysis. Highly recommended!
I think the most difficult part to convey and justify is the gird-connected vs off-grid argument. At 7.5% cost of capital and 20 year return, off-grid solar is still north of $30/MWh if on the same balance sheet. Signing a PPA for lower cost solar still needs the grid as backup offtaker unless the kerosene buyer’s offtake contract is backed by ultra-creditworthy partner(s).
Realistically, that’ll necessitate the grid connection, and drive the ability to pile PPAs from multiple solar (and wind) sites. While that will boost uptime, it’ll compete with other new sources of power demand. The ‘flexible load’ nature is key, just as you’ve said, but I suspect it’ll require you to set up relationships with VPP partners (and in grids where this is allowed).
And the inevitable question is, if you can make FT flexible, in what year will data centers start operating more flexibly? and what will that do to grid power competition?